
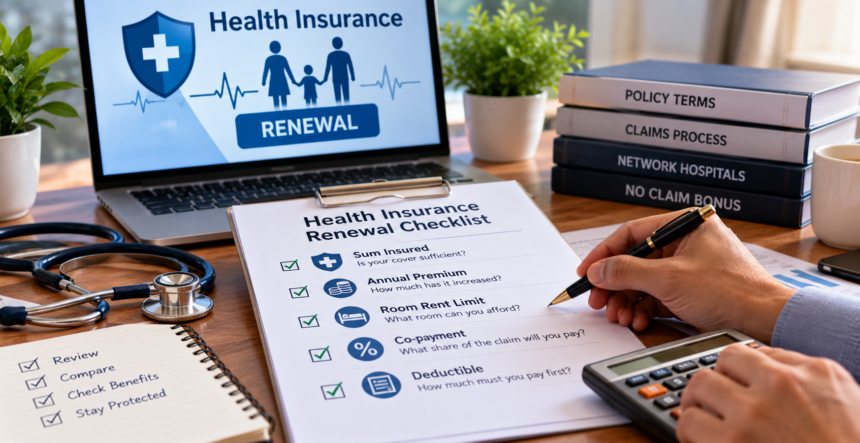
Renewing a health insurance policy is an important opportunity to ensure that your coverage continues to meet your medical and financial needs. Simply paying the premium before the due date may not be enough. Policyholders should also review their coverage limits, premium changes and policy conditions to understand whether their existing plan still offers adequate protection.
Medical expenses can change over time, while personal circumstances, family requirements and insurance terms may also evolve. A policy that provided sufficient coverage a few years ago may no longer be suitable for your current needs.
Before renewing your health insurance, review five key policy details. Checking these figures and conditions can help you understand your potential out-of-pocket expenses and avoid unexpected difficulties during a claim.
1. Sum Insured: Is Your Health Cover Enough?
The sum insured is the maximum amount available under a health insurance policy, subject to its terms, conditions and applicable limits. It is one of the most important factors to review at renewal.
Hospitalisation and treatment costs can vary depending on the city, hospital and type of medical care required. As a result, coverage that was sufficient when you purchased the policy may not meet your needs today.
Review your existing sum insured against the potential cost of medical treatment in your area. If the coverage appears inadequate, explore options for increasing it, subject to the insurer’s terms and eligibility requirements.
A qualified financial adviser can help you assess whether your coverage aligns with your financial situation and protection needs.
2. Annual Premium: Why Has the Cost Changed?
Before making a renewal payment, compare the new premium with the amount you paid last year. Understanding any increase or decrease can help you evaluate the policy’s overall cost.
Premiums may change because of age-related pricing, revisions to the insurer’s rates or adjustments to the coverage selected. If the difference is significant, contact your insurer to understand the reasons.
You can also compare other available policies to see whether they offer suitable coverage at a reasonable cost. However, do not compare premiums alone. Examine benefits, waiting periods, exclusions and other conditions before switching to another plan.
The objective should be to balance affordability with the level of protection you require.
3. Room Rent Limit: Which Hospital Room Is Covered?
Some health insurance policies specify a daily room rent limit or restrict the category of hospital room a policyholder can choose. Reviewing this condition before renewal can help prevent unexpected expenses during hospitalisation.
Depending on the policy terms, choosing a room that exceeds the permitted limit may lead to proportionate deductions on certain associated medical expenses. The impact can vary according to the specific policy provisions.
Check whether your existing room rent limit remains suitable for the hospitals you may use in your city. Also review any changes to the room eligibility conditions before renewing the policy.
Understanding these restrictions in advance can help you make a more informed decision about your coverage.
4. Co-payment: How Much of the Claim Must You Pay?
A co-payment clause requires the policyholder to pay a specified percentage of an admissible medical claim, while the insurer pays the remaining eligible amount, subject to the policy’s terms and conditions.
For example, suppose a policy has a 20% co-payment requirement and the admissible claim amount is ₹2 lakh. The policyholder would pay ₹40,000, while the insurer would cover the remaining ₹1.60 lakh, subject to other applicable conditions.
Before renewing, check whether your policy includes a co-payment clause and whether the percentage changes at particular ages or under specific coverage conditions.
Do not assume that every term will remain unchanged from one renewal to the next. If any clause is unclear, contact your insurer’s customer service team for clarification.
5. Deductible: What Must You Pay Before Coverage Begins?
A deductible is the amount the policyholder must bear before the insurer begins paying eligible expenses under the relevant coverage, in accordance with the policy terms.
This condition deserves particular attention if you have a super top-up health insurance policy. Such policies generally cover eligible medical expenses above a specified deductible, subject to their conditions.
Review the deductible amount and check whether it remains appropriate in relation to your base health insurance policy and your ability to pay medical expenses from your own funds.
A deductible that is too high for your financial circumstances could leave you responsible for a substantial amount before the additional coverage becomes applicable.
Additional Checks Before Renewing Health Insurance
Along with these five key details, review the waiting periods applicable to pre-existing diseases and specific treatments. Check whether your accumulated no-claim bonus (NCB), if any, is reflected correctly in the renewal terms.
It is also important to verify the insurer’s current network hospital list. These lists can change, so confirm whether hospitals that are convenient for you remain part of the network.
Taking time to review these conditions can help you understand your coverage, identify possible gaps and make a more informed renewal decision.
Disclaimer: This article is intended for general informational and educational purposes only and does not constitute financial, insurance or medical advice. Coverage limits, co-payments, deductibles, room rent restrictions and other benefits vary by policy. Always read the policy wording and renewal documents carefully, and contact your insurer or a qualified insurance adviser for guidance specific to your circumstances.