
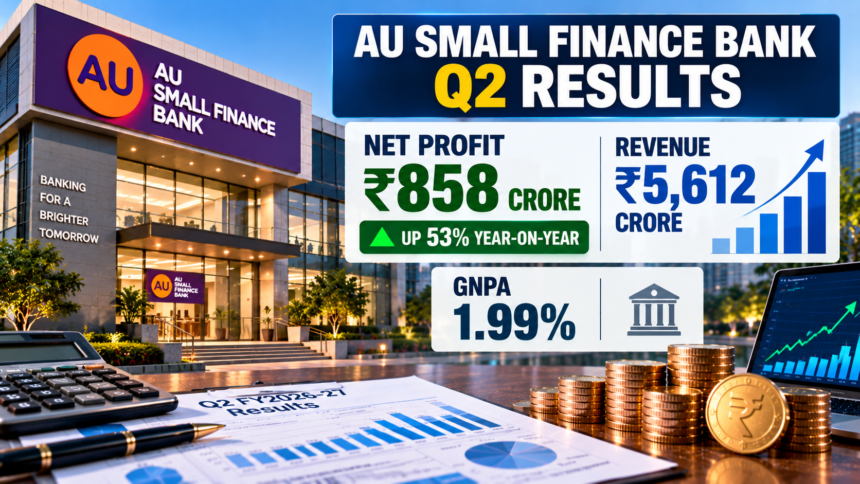
AU Small Finance Bank reported a strong rise in profitability for the July–September quarter of FY2026–27, with net profit increasing 53% year-on-year to ₹858 crore. The improvement came alongside better asset-quality indicators and lower provisions for potential loan losses.
The quarterly performance highlights the lender’s progress in managing credit risk while continuing to grow its banking business.
Profit Growth Strengthens Quarterly Performance
AU Small Finance Bank’s net profit climbed from ₹561 crore in the corresponding quarter last year to ₹858 crore in the latest quarter. Revenue rose 24% year-on-year to ₹5,612 crore, reflecting stronger overall business performance.
The growth in earnings is an important indicator for investors, although sustained profitability will also depend on funding costs, loan demand and the bank’s ability to manage credit risk.
Bad-Loan Indicators Improve
The bank reported an improvement in its asset-quality metrics. Its gross non-performing asset (GNPA) ratio fell by 42 basis points to 1.99% at the end of September. The net NPA ratio improved by seven basis points to 0.81%.
A lower NPA ratio generally indicates that a smaller share of a lender’s loan book is classified as non-performing. Investors typically track these figures to assess the health of a bank’s lending portfolio.
Provisions and Credit Costs Decline
Provisions for potential bad loans fell by 25% to ₹359 crore, compared with ₹481 crore a year earlier. The bank’s annualised credit cost also improved to 0.8%, from 1.2% in the year-ago period.
Lower provisions can support reported profits, but investors will want to see whether the improvement continues as the loan book expands and economic conditions evolve.
What Investors Should Watch
AU Small Finance Bank’s latest results show stronger profit, higher revenue and improved asset-quality measures. Going forward, deposit growth, lending trends, credit costs and profitability will remain important indicators to monitor.
The results alone do not determine how the share price will perform. Investors should also consider the bank’s valuation, future business outlook and broader market conditions before making financial decisions.