
The Central Board of Direct Taxes (CBDT) has proposed a new reporting requirement for taxpayers claiming tax exemptions on interest income and capital gains earned from certain government securities.
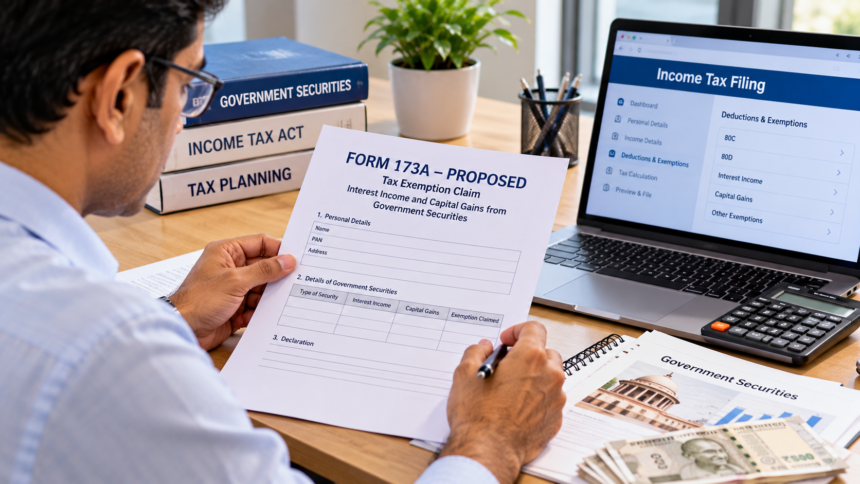
Under the proposed Income-tax (Seventh Amendment) Rules, 2026, the tax department plans to introduce Rule 281A and Form 173A under the Income-tax Act, 2025. The move aims to improve reporting and documentation of income claimed as exempt under Schedule IV.
What Is Form 173A?
The proposed Form 173A will be used by eligible taxpayers to provide information when claiming exemptions on specified interest income and capital gains from government securities.
The form is intended to collect details relating to eligible assets, income received and government securities purchased or sold during the relevant tax year.
Who Could Be Affected?
The proposed requirement is relevant to taxpayers who earn income from government securities and claim exemptions under the applicable provisions of Schedule IV.
Investors may need to provide additional information to support their exemption claims once the new rules become applicable.
Why Is CBDT Introducing This Change?
The proposed reporting mechanism is aimed at improving transparency and making it easier for tax authorities to verify exemption claims.
By collecting more structured information, the department intends to strengthen tax reporting and reduce discrepancies in exemption-related disclosures.
What Should Taxpayers Know?
It should not be treated as a final implemented rule until the government completes the applicable notification process.
Taxpayers investing in government securities should keep track of the final rules and any subsequent instructions issued by CBDT.
The proposed Form 173A is another development under the new Income-tax Act framework, which is bringing changes to tax compliance and reporting procedures.