
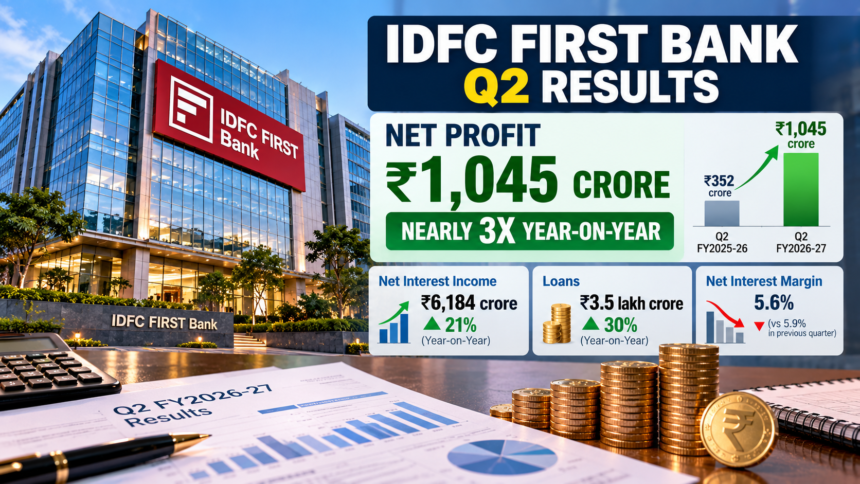
IDFC First Bank reported a sharp improvement in its financial performance for the July–September quarter of FY2026–27, with net profit rising to ₹1,045 crore from ₹352 crore in the same quarter last year. The result, reported on October 25, 2026, reflects stronger loan growth and higher fee income.
The lender also recorded an increase in net interest income, although its net interest margin declined compared with the previous quarter.
Net Interest Income Rises 21%
The bank’s net interest income (NII)—the difference between interest earned on loans and interest paid on deposits—increased 21% year-on-year to ₹6,184 crore, compared with ₹5,113 crore a year earlier.
Growth in lending helped support the bank’s core income during the quarter. Fee income also contributed to the improvement in profitability.
Loan Book Expands by 30%
IDFC First Bank’s loans, including credit substitutes and lending backed by FCNR(B) deposits, increased 30% year-on-year to approximately ₹3.5 lakh crore.
Excluding loans secured by FCNR(B) deposits, loan growth stood at 22%. This indicates continued expansion in the bank’s lending business.
Net Interest Margin Declines
Despite stronger earnings, the bank’s net interest margin (NIM) fell to 5.6% from 5.9% in the June 2026 quarter. The decline was partly linked to the cost associated with loans used to attract FCNR(B) deposits.
NIM is an important banking indicator because it measures the difference between the interest a bank earns and the interest it pays relative to its interest-earning assets.
What Investors Should Watch Next
Investors will be watching whether the bank can maintain loan growth while managing funding costs and protecting its margins. Asset quality, deposit growth and future earnings will also be important indicators of its financial performance.
The profit increase is a positive development in the reported quarter, but it does not guarantee that the bank’s share price will rise. Market prices also reflect valuation, expectations and broader financial conditions.