
In an important income tax ruling, the Jaipur Bench of the Income Tax Appellate Tribunal (ITAT) has granted relief to an insurance agent who faced a tax dispute after depositing ₹35 lakh in cash into his bank account.
The case involved cash collected from policyholders as insurance premiums. The Income Tax Department had treated the deposits as unexplained money, but the agent argued that the amount belonged to customers and was collected on behalf of insurance companies.
The tribunal’s decision highlights the importance of proper documentation when handling customer payments and large cash deposits.
Tribunal Accepts Documents Supporting the Agent’s Explanation
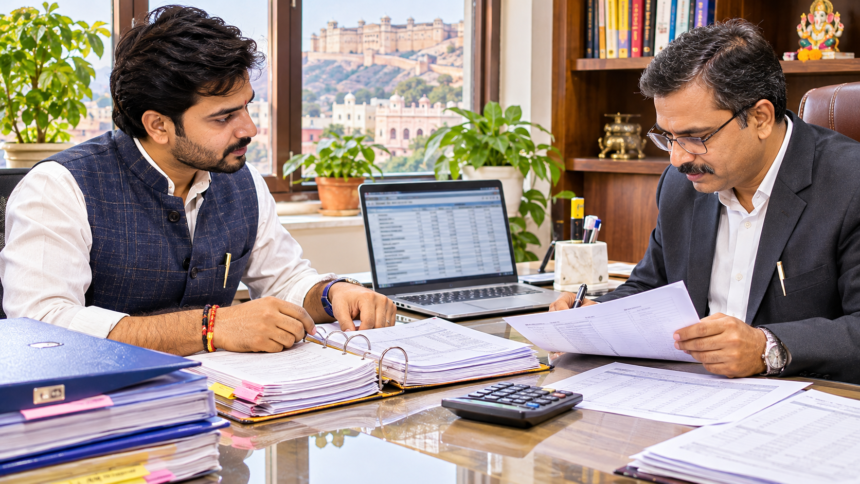
The agent, identified as S.K. Sharma from Neem Ka Thana in Rajasthan, submitted several documents to support his explanation, including:
- Insurance policy registers.
- Cash-flow statements.
- Bank transaction records.
- Affidavits from other insurance agents.
- Records showing commission payments through banking channels.
These documents helped establish that the cash was collected as part of his insurance-related business activities.
₹35.08 Lakh Tax Addition Ordered to Be Deleted
The Jaipur ITAT found that the lower appellate authority had not properly considered the evidence submitted by Sharma. It observed that the involvement of other insurance agents did not automatically make his explanation invalid.
The tribunal set aside the earlier appellate order and directed that the ₹35,08,550 tax addition be deleted.
The ruling was delivered on October 1, 2026, and became a significant development in the case reported on November 4.
Important Lesson for Taxpayers
The decision highlights why maintaining proper financial records is important when dealing with substantial cash transactions.
Taxpayers should preserve payment receipts, bank statements and supporting documents to explain the source and purpose of transactions whenever required.
The ruling relates to the specific facts and evidence of this case. It does not mean that every large cash deposit is automatically exempt from income tax scrutiny.