
When an employee dies while in service, the family may face financial difficulties along with the emotional loss. The money accumulated in the employee’s Employees’ Provident Fund (EPF) account can provide financial support, but family members need to understand the claim process, eligibility requirements and documents involved.
Under the applicable EPFO procedures, a registered nominee or another eligible claimant can apply for the amount in the deceased employee’s account. Knowing the required steps can help families avoid unnecessary delays.
What Happens to a PF Account After an Employee’s Death?
The accumulated provident fund balance does not automatically disappear when an employee dies. The registered nominee can submit a claim to receive the eligible amount, subject to the applicable EPFO rules.
Families should first confirm the employee’s PF account details and check whether a nominee has been registered. They can then gather the necessary documents and submit the claim through the prescribed process.
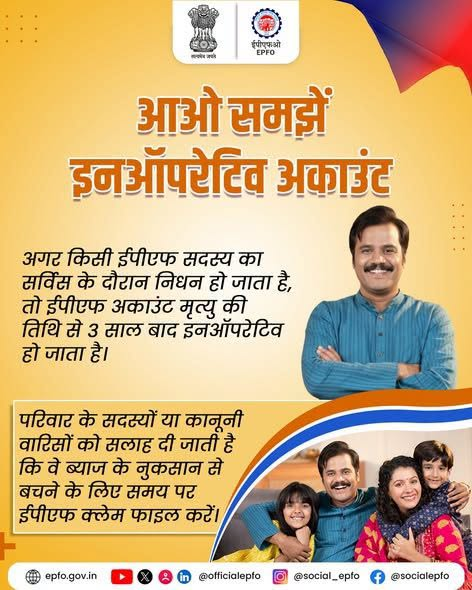
What Happens If the PF Claim Is Delayed for Three Years?
The source article states that an unclaimed PF amount may be placed in the inoperative-account category after 36 months. However, the treatment of an account depends on the applicable EPFO rules and the account’s status.
An account becoming inoperative does not, by itself, mean that the accumulated money is automatically forfeited. Families should not assume that they lose their entitlement simply because a claim was not filed within three years.
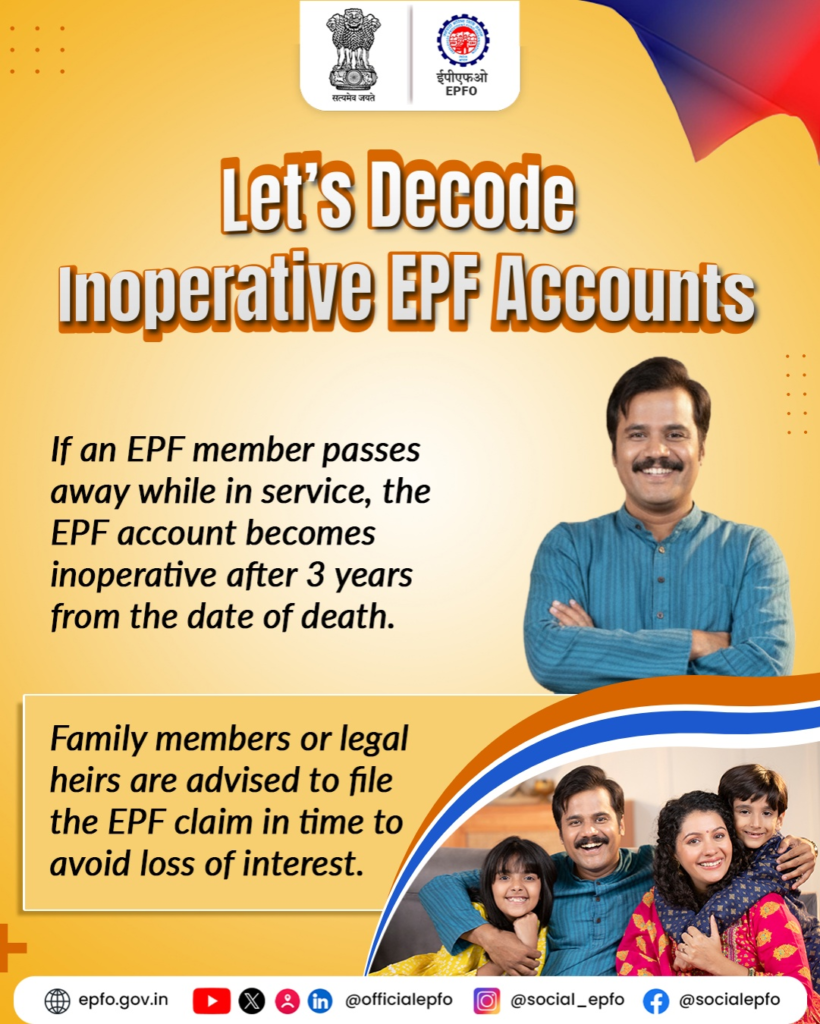
It is advisable to contact EPFO or check the official guidance applicable to the account to understand its current status, interest treatment and claim requirements.